Personal insurance review
Loading or exclusion on your personal insurance?
It might be time to challenge it.
Personal insurance is expensive. If you're paying thousands of dollars every year for your cover, you want to make sure you're getting as much value from your policy as possible.
If you have a loading or exclusion that was applied years ago, there may be an opportunity to have it reviewed — and potentially removed.
We'll review your existing insurance at no cost and find out.
An underwriting decision from years ago doesn't always need to follow you forever
Maybe you injured your back ten years ago. Maybe you went through a difficult period with your mental health. Maybe you had a medical issue that was significant at the time, but hasn't troubled you for years.
When you applied for insurance, your insurer assessed the risk as it existed at that point in time. And based on your circumstances, they may have applied an exclusion or increased your premium with a loading.
That may have been entirely reasonable. But your circumstances can change. Your health can improve. Years can pass without symptoms or treatment. Medical issues can resolve.
The terms of your insurance should improve alongside these changes.
Your insurer isn't going to review it for you
An exclusion can remain on a policy for years — even where the circumstances that originally caused it have changed. That's because these reviews don't happen automatically.
Your insurer won't routinely contact you and ask whether an exclusion can now be removed, or whether you should still be paying a loading. If nobody challenges the original decision, it remains in place.
For people with an advisor actively looking after their insurance, this should be part of the ongoing job: understanding when amended terms can be reviewed, diarising the opportunity and going back to the insurer when the time comes.
But many Australians have insurance policies that were established years ago through an adviser they no longer speak to, or through a bank that no longer provides personal financial advice.
The policy remains.
The premiums keep getting paid.
But nobody is actively looking after it.
Insurance is too expensive not to get it right
Think about what you're paying for.
Income protection, TPD and other personal insurance exist to protect you against some of the biggest financial risks you'll ever face.
An exclusion creates a gap in that protection. A loading means you're paying more for it. And when personal insurance can cost thousands of dollars every year, it's worth asking whether terms applied years ago still need to be there today.
Not every loading or exclusion can be removed. But the ones that can be removed are worth finding.
Because removing an exclusion doesn't just improve your policy this year. It can improve the protection you have for years to come.
A real review
We've seen what a difference it can make
We recently served a member who had held the same insurance policy for eight years. Their policy contained a full back exclusion and a mental health exclusion.
Those exclusions had remained on the policy since inception. Nobody had gone back to review them.
We investigated why the exclusions had originally been applied, obtained updated medical information and approached the insurer to reconsider the terms based on the client's circumstances today.
The insurer agreed to remove both exclusions. No application form. No new policies.
Just better terms.
The policy simply became substantially better than it had been before.
Not every review produces that outcome. But this member had spent eight years carrying exclusions that ultimately didn't need to remain there. That's exactly why we think old exclusions are worth challenging.
Let us do the work
Our insurance review is free.
We'll look at your existing policy, understand the loading or exclusion you're concerned about and establish why it was originally applied.
Then we'll speak with the insurer and determine whether there's an opportunity to have it removed.
At the end of the review, you'll know:
— Why the loading or exclusion exists (what drove the insurer's original underwriting decision)
— Whether it can be reviewed now
— What is required to have it removed
— If it can't be removed today, when you can try again
— If no improvement is available, whether there are better options available elsewhere

You don't need to know whether your exclusion is reviewable. That's our job.
You don't need your old underwriting paperwork. You don't need to know exactly why the insurer made its original decision. And you don't need to call an underwriting department and try to navigate the process yourself.
Start with the policy you already have. We'll take it from there.
You've paid for the insurance. Make sure you're getting the best cover you can from it.
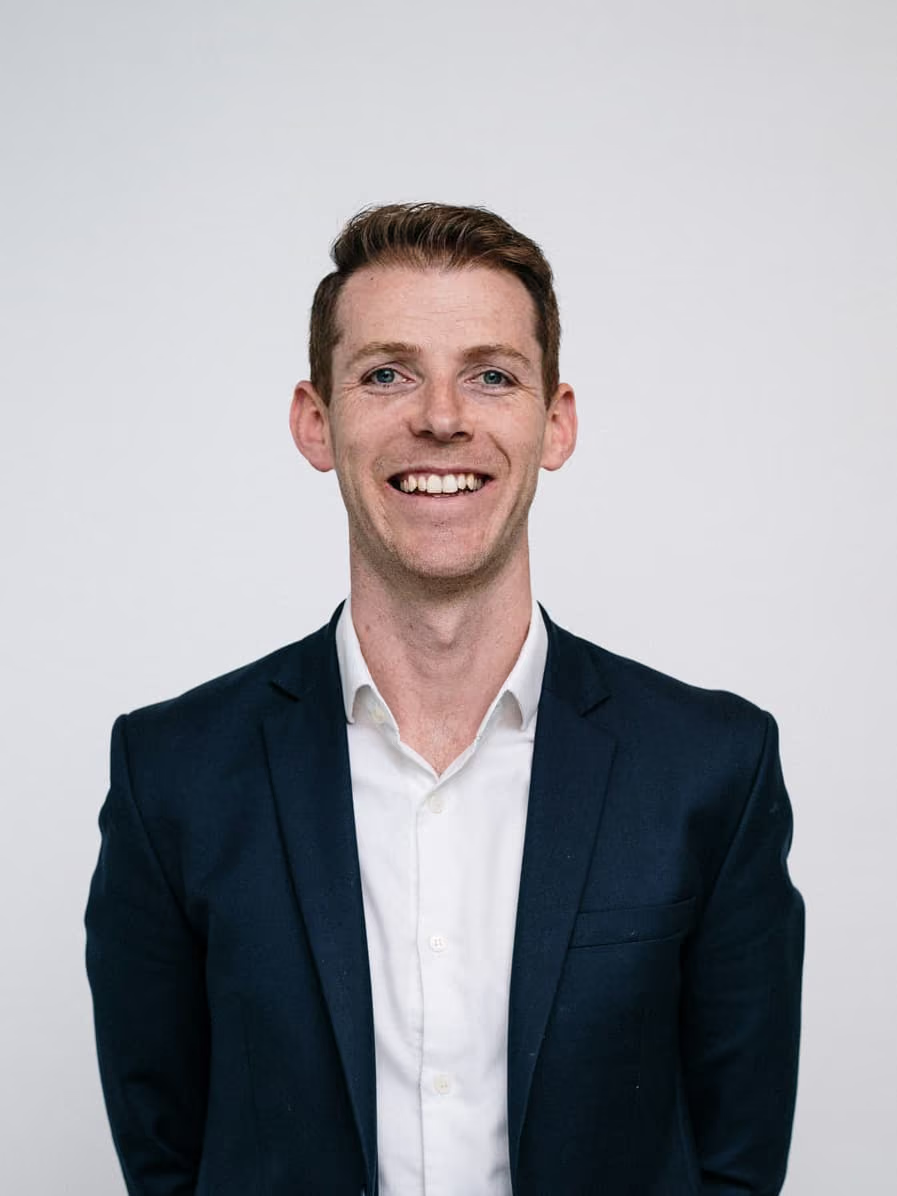
Your reviewer
James O'Reilly
James O'Reilly is the Founder, Director and Financial Advisor at Northeast Wealth, an award-winning financial planning firm based in Melbourne, Australia. With nearly three decades of experience in the finance industry, he specialises in retirement planning, investment management and behavioural coaching.