Make more of what you earn
A good income should give you options. The ability to enjoy life today, make progress towards your financial goals and build wealth for the future.
But between mortgage repayments, household expenses, family commitments and other financial priorities, even a strong income can be stretched. You might be earning more than ever, whilst knowing you're not making the most of it.
Effective cash flow management is about more than tracking expenses or sticking to a budget. It's about understanding what you can afford, making better use of your income and having a clear plan for the money you have available.
At Northeast, we help you make informed decisions about how much to spend, save, invest and put towards debt. We consider your cash flow alongside your broader financial position, including tax, superannuation, investments and retirement planning.
The result is a financial strategy that helps you enjoy your money today while making meaningful progress towards your future.
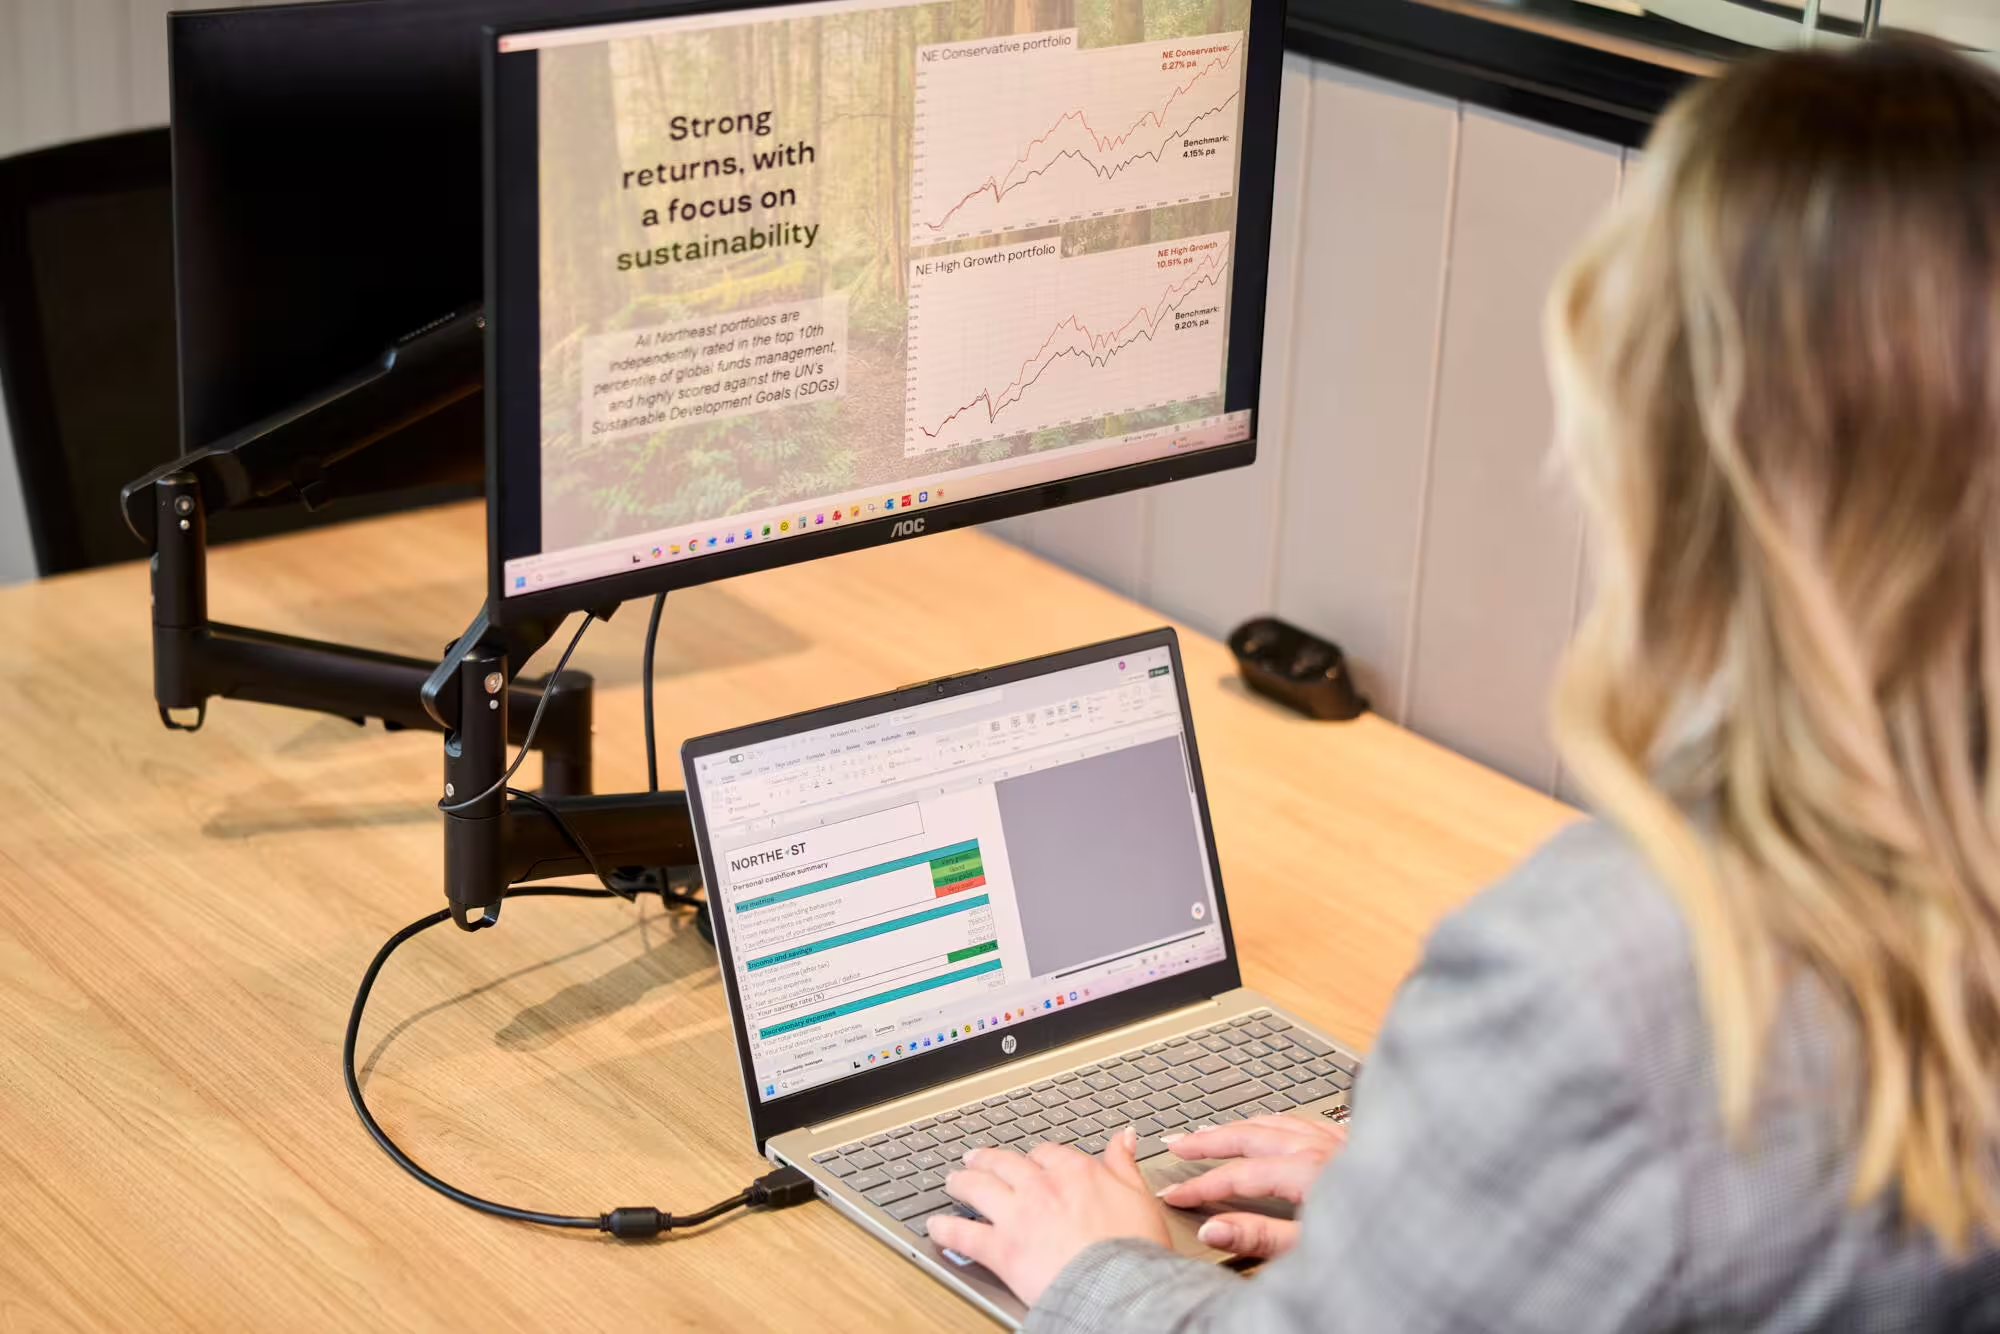
How we help you make more of your income
Understand your financial position
Before making decisions about where your money should go, it helps to understand where you stand.
We review your household income, expenditure, debt repayments, savings and financial commitments to build a clear picture of your cash flow.
This allows us to identify how much you have available, where improvements might be made and what your current financial arrangements mean for your longer-term goals.
Make better financial decisions
When you have money available, deciding what to do with it isn't always straightforward.
Should you make extra mortgage repayments? Contribute more to super? Build an investment portfolio? Or enjoy more of your income today?
We help you compare these options, considering factors such as tax, investment returns, interest costs, risk and access to your money.
Our goal is to help you direct your income towards the opportunities that make the most sense for your circumstances.
Plan for what's ahead
Your income and expenditure will change throughout your life. The financial demands of raising a family can look very different from those of your final working years or retirement.
We help you plan for these changes by modelling your future cash flow, major expenses and financial commitments.
Whether you're considering a career change, working fewer days, making a significant purchase or bringing forward your retirement, we help you understand what you can afford and the potential impact on your financial future.
Keep your strategy on track
A cash flow strategy shouldn't be something you establish once and forget.
As your income, expenses and priorities change, the way you use your money should change too.
Through ongoing financial advice, we review your progress, revisit your priorities and adjust your strategy where needed.
This helps you make informed financial decisions throughout the different stages of your life.
Frequently asked questions about budgeting and cash flow
Cash flow management is the process of understanding how money moves through your household and deciding how best to use it.
It considers your income, living expenses, debt repayments, savings and investments, as well as future financial commitments.
While budgeting is an important part of cash flow management, a broader strategy also considers how your income can support goals such as reducing debt, building wealth and preparing for retirement.
A higher income doesn't always translate into greater financial flexibility.
For many households, their peak earning years also coincide with their highest expenses. Mortgage repayments, school fees, family commitments and lifestyle costs can absorb a significant proportion of their income.
The challenge isn't always how much you earn, but how your income is allocated.
Reviewing your cash flow can help identify opportunities to improve your financial position, whether through spending decisions, debt management, tax planning or redirecting more of your income towards wealth creation.
Both approaches can improve your financial position, but they deliver different benefits.
Making additional mortgage repayments can reduce interest costs and provide a relatively predictable financial benefit. Investing offers the potential for long-term growth, although returns aren't guaranteed and your money is exposed.
Superannuation contributions may also be worth considering, particularly where tax concessions can improve the outcome.
The right approach depends on your mortgage interest rate, tax position, investment timeframe, risk tolerance and need to access your money.
We help you compare these strategies so you can make an informed decision about where your surplus income should go.
Improving cash flow doesn't always require reducing your spending.
Depending on your circumstances, opportunities might include restructuring debt, reviewing loan arrangements, improving tax efficiency or changing how your savings and investments are managed.
It can also involve planning ahead for larger expenses and making more deliberate decisions about how your income is allocated.
The objective is to find a balance that allows you to enjoy your current lifestyle while continuing to make financial progress.
This is an important question, particularly as you move through your 50s and 60s.
Spending too much today could limit your future options. But being unnecessarily conservative can mean missing opportunities to enjoy the wealth you've worked hard to build.
We use financial modelling to help you understand how your spending, savings, investments and retirement timing interact.
By considering your current financial position and projected retirement needs, we can help you establish a spending level that supports your lifestyle while maintaining an appropriate level of confidence in your longer-term financial position.
Yes. A financial advisor can help you understand your cash flow and, more importantly, how to use your income to achieve your broader financial goals.
At Northeast Wealth, our advice goes beyond preparing a household budget.
We consider how your spending, debt, savings, investments, superannuation and retirement plans work together, helping you make informed decisions about the money you earn and the wealth you're building.


.avif)